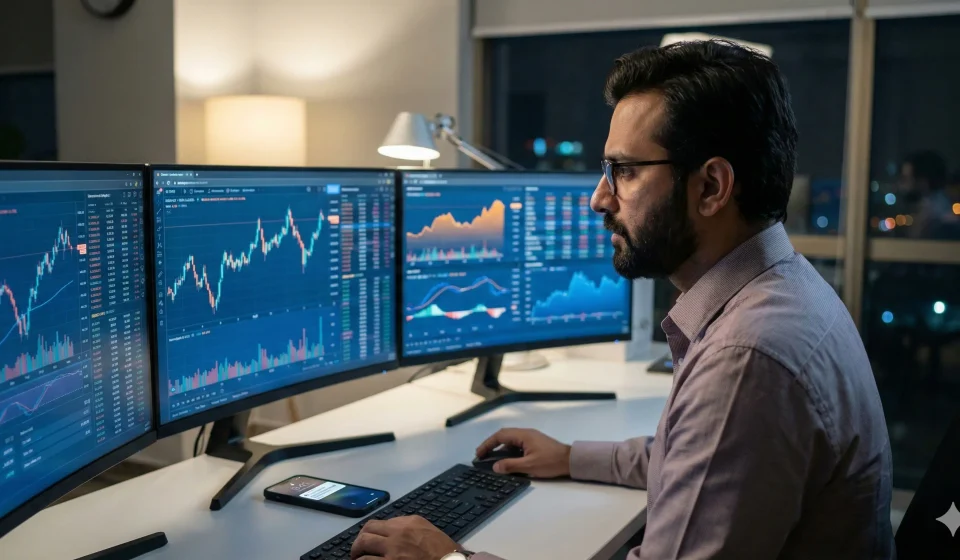

Finance www disquantified .org are easier to evaluate when reliable information replaces guesswork. Whether someone is managing a household budget, researching investments, or evaluating a business opportunity, understanding financial data can help reveal risks, identify priorities, and support better long-term planning. As digital finance continues to evolve, people are increasingly looking for accessible resources that explain complex financial information in practical terms.
The search phrase finance www disquantified .org suggests an interest in financial information associated with Disquantified.org. However, a search phrase alone does not establish what the website offers, who operates it, or whether its content has been independently verified. Readers should evaluate the site’s actual material before relying on it for financial decisions.
More broadly, exploring finance through data analysis provides a useful starting point for understanding personal money management, investing, business performance, and economic trends. The key is learning how to interpret financial information, assess its reliability, and apply it to real-world situations without overlooking uncertainty.
What Does Finance Mean in a Data-Driven World?
Finance involves managing money, allocating resources, evaluating risk, and planning for future financial needs. It includes personal finance, corporate finance, public finance, and investment management.
Traditionally, many financial decisions relied on paper statements, professional advice, historical reports, and individual experience. Digital tools now make it easier to compare financial information, track changes over time, and analyze a wider range of variables.
For example, a household can review several months of spending to identify unnecessary expenses. A business owner can compare revenue with operating costs to determine whether sales growth is translating into profit. An investor can examine a company’s earnings, debt, and cash flow before deciding whether to research its stock further.
These examples demonstrate an important principle: financial data becomes useful when it answers a specific question.
Simply collecting numbers is not enough. Users must understand what the figures represent, where they originated, how recently they were updated, and what limitations might affect their interpretation.
What Can Readers Find on Disquantified.org’s Finance Section?
Disquantified.org has a dedicated finance category featuring articles about money management, borrowing, and investing. Its content is presented primarily in a blog format, making it different from a financial institution, brokerage account, or dedicated financial analytics application. Disquantified+1
Readers exploring the website can use its published articles as a starting point for learning about financial topics. The value of any individual article depends on its accuracy, sources, publication date, and relevance to the reader’s situation.
Personal Finance and Budgeting
Personal finance covers everyday decisions about income, spending, savings, debt, and future goals. These subjects are relevant to students, working professionals, families, and retirees.
A useful budgeting approach begins with a clear picture of monthly cash flow. Consider a household with a monthly take-home income of $4,000. If essential expenses total $2,500, debt payments are $400, and discretionary spending is $600, the household has $500 remaining for additional savings or other priorities.
This simple example illustrates how tracking income and expenses can reveal opportunities to improve financial stability.
A practical budgeting process includes:
- Recording income from all reliable sources.
- Separating essential expenses from optional purchases.
- Reviewing debt payments and interest costs.
- Setting realistic savings targets.
- Checking spending patterns regularly and adjusting when circumstances change.
The objective is not to eliminate every enjoyable expense. Finance www disquantified .org It is to ensure that current spending supports both immediate needs and longer-term financial goals.
Saving and Emergency Funds
Savings provide flexibility when unexpected expenses arise. A car repair, temporary loss of income, medical bill, or urgent home repair can disrupt a budget if no reserves are available.
An emergency fund helps cover these expenses without immediately relying on credit cards or high-interest borrowing.
The appropriate savings target depends on income stability, household responsibilities, fixed expenses, and access to other resources. Someone with variable freelance income may need a larger cash reserve than someone with predictable earnings and substantial financial support.
A practical starting point is to establish a small, achievable savings goal and increase it over time. Keeping emergency savings accessible and separate from everyday spending can make it easier to preserve the money for genuine emergencies.
Investing and Financial Markets
Investment education helps readers understand the relationship between potential returns, risk, time horizons, and financial objectives.
Common investment categories include stocks, bonds, mutual funds, exchange-traded funds, and certain real estate investments. Each has different characteristics, costs, and risks.
For example, stocks represent ownership interests in companies and can experience substantial price fluctuations. Bonds generally involve lending money to an issuer under specified terms, although their prices and repayment prospects can also change. Diversified funds provide exposure to multiple securities, but diversification does not eliminate the possibility of losses.
Before researching an investment, readers should consider:
- Their investment time horizon.
- Their ability to withstand losses.
- Management fees, trading costs, and taxes.
- The diversification of their portfolio.
- Whether the investment fits their overall financial plan.
Financial articles can help explain these concepts, but an article’s confident tone does not establish that its investment recommendations are appropriate for every reader.
How to Evaluate Financial Information Online
The availability of online financial content makes education more accessible, but it also creates a challenge: readers must distinguish well-supported explanations from unsupported claims and promotional material.
This is especially important when searching for a particular website, including queries such as finance www disquantified .org.
Rather than judging a resource by its name or appearance, Finance www disquantified .org evaluate the evidence behind its claims.
Check the Author’s Credentials
A financial article should identify its author or provide enough information to establish editorial accountability. When an author claims professional expertise, readers should look for relevant qualifications and verifiable experience.
For investment advice, it is particularly important to distinguish general financial education from recommendations made by a qualified professional.
In the United States, readers can use the SEC’s investment adviser resources and FINRA BrokerCheck to investigate relevant registrations, employment histories, and disciplinary disclosures where applicable.
A missing credential does not automatically make every statement incorrect. However, unclear authorship is a reason to seek independent confirmation before acting on high-stakes information.
Look for Reliable Sources
Strong financial content makes important claims verifiable.
For example, an article discussing inflation should identify the relevant data or explain where the figures came from. An explanation of federal tax rules should be consistent with current Internal Revenue Service guidance. A discussion of investment products should account for their risks, costs, and relevant regulatory disclosures.
Useful primary sources include government statistical agencies, regulators, official company filings, and the original documentation for financial products.
Readers should be especially cautious when an article includes impressive return figures, dramatic market predictions, or claims about financial products without explaining the underlying evidence.
Check the Publication Date
Financial information can become outdated quickly.
Interest rates change, tax thresholds are revised, investment products introduce new fees, and regulations evolve. Even a well-written article can become misleading when its information no longer reflects current conditions.
Before relying on a financial guide, check its publication date and whether the author has updated it. Verify time-sensitive claims against current official sources.
This is particularly important for content about loans, credit cards, retirement contributions, tax planning, and market conditions.
Identify Promotional Content
Some finance articles are designed partly to generate revenue through advertising, affiliate links, sponsorships, or referrals.
Commercial content is not automatically inaccurate, but financial incentives can affect which products receive attention and how their benefits are described.
Readers should ask whether an article clearly discloses commercial relationships, presents meaningful drawbacks, and compares alternatives fairly.
A recommendation that emphasizes potential returns while ignoring fees, losses, liquidity restrictions, or borrowing costs deserves additional scrutiny.
How to Apply Financial Knowledge to Everyday Decisions
Financial education is most valuable when it leads to practical improvements. Readers do not need advanced mathematics or professional investment software to begin making more informed decisions.
A straightforward process can help turn general financial knowledge Finance www disquantified .org into useful action.
Step 1: Define the Financial Goal
Start by identifying the decision you need to make.
You might want to reduce credit card debt, build emergency savings, prepare for retirement, or evaluate whether a large purchase fits your budget.
A specific goal makes it easier to identify which information matters and which information is merely interesting.
Step 2: Gather Relevant Numbers
Collect the figures directly connected to the decision.
For debt repayment, these might include outstanding balances, interest rates, minimum payments, and available monthly cash flow. For a major purchase, consider the initial price, recurring expenses, financing costs, and maintenance requirements.
Use current statements and original documents whenever possible instead of relying entirely on estimates from online articles.
Step 3: Compare Realistic Alternatives
Consider at least two reasonable options before committing.
Suppose you have an extra $200 each month. You might use it to accelerate high-interest debt repayment, build an emergency reserve, or contribute to a long-term investment account.
The best option depends on your existing savings, borrowing costs, financial security, and time horizon. Comparing these factors helps prevent a decision based on a single appealing number.
Step 4: Account for Risk and Uncertainty
Financial projections are not guarantees.
Investment returns fluctuate, household expenses can rise unexpectedly, and income may change. A plan that works only under optimistic assumptions can become difficult to maintain when circumstances deteriorate.
Consider a less favorable scenario before making an important commitment. Ask whether you could still meet essential expenses if income fell, borrowing costs increased, or an investment lost value.
Step 5: Review the Results
Monitor the decision over time and make adjustments when necessary.
A monthly budget can be reviewed every few weeks, while retirement planning and long-term investment strategies may require less frequent but more comprehensive assessments.
The aim is to establish a repeatable decision-making process rather than constantly reacting to individual headlines or short-term market movements.
The Role of Technology in Modern Financial Management
Financial technology has changed how individuals organize money and evaluate financial information.
Banking applications, budgeting software, brokerage platforms, and spreadsheet tools can make it easier to monitor transactions, identify spending patterns, and track progress toward financial goals.
However, technology is most useful when its limitations are understood.
Financial Dashboards and Budgeting Tools
A dashboard can bring multiple financial figures into one view, allowing users Finance www disquantified .org to compare income, expenses, debt, and savings.
For example, a monthly spending report may reveal that subscription fees and dining expenses have gradually increased. Seeing the combined cost can help a household decide whether those expenses still fit its priorities.
The figures still need interpretation. A dashboard may categorize a transaction incorrectly, omit an account, or display incomplete information if a connection fails.
Users should periodically compare digital summaries with original account statements.
Automation and Financial Habits
Automatic transfers can help people maintain consistent saving habits. Scheduling a transfer shortly after payday may reduce the temptation to spend money intended for future goals.
Automation can also support recurring bill payments, although account balances and payment dates should be monitored to avoid overdrafts or missed obligations.
The most effective system is one that fits the user’s income pattern and remains flexible when circumstances change.
Artificial Intelligence and Financial Analysis
AI-powered tools can summarize documents, explain financial terminology, categorize expenses, and help users explore different budgeting scenarios.
They can also produce inaccurate explanations, overlook important qualifications, or rely on outdated information. A polished response is not proof that a calculation or financial claim is correct.
Use AI as an aid to understanding rather than as the final authority on taxes, investments, legal obligations, or major financial commitments. Verify consequential information using original documents and appropriate professional resources.
Common Financial Mistakes to Avoid
Even people who regularly read financial content can make avoidable mistakes. Awareness of common problems can improve the quality of everyday financial decisions.
Confusing Revenue With Profit
For a business, revenue is the money generated through sales, while profit reflects what remains after applicable expenses. A company can report increasing revenue while experiencing declining profitability because its costs are rising even faster.
Business owners should review expenses, operating margins, cash flow, and debt obligations rather than judging performance from sales figures alone.
Ignoring the Cost of Debt
The monthly payment on a loan does not tell the whole story. Interest rates, fees, repayment periods, and penalties can materially affect the total cost of borrowing.
Before accepting a loan, compare the annual percentage rate where applicable, total repayment amount, repayment schedule, and conditions that could increase costs.
Chasing Short-Term Market Trends
Investment decisions driven by fear of missing out can encourage excessive trading and exposure to risks that do not fit a person’s financial circumstances.
A disciplined investment strategy begins with goals, risk tolerance, diversification, and costs. Short-term market movements should be evaluated within that broader context rather than treated as automatic signals to buy or sell.
Treating Online Opinions as Verified Facts
A popular article, social media post, or confident prediction may still be inaccurate.
Look for evidence, transparent assumptions, independent confirmation, and clear explanations of uncertainty. Avoid committing money solely because a website presents a strategy as easy, exclusive, or guaranteed to succeed.
Frequently Asked Questions
What is finance www disquantified .org?
The phrase appears to be a search query for financial content associated with Disquantified.org. The website has a finance article category covering money-related topics. Readers should verify the exact domain and assess individual articles before relying on their claims. Disquantified+1
Is Disquantified.org a financial services platform?
Disquantified.org publishes articles in a blog format. Its finance category should not be confused with a brokerage, bank, or dedicated financial analysis application. Check the site’s current offerings directly rather than assuming that published articles indicate access to financial tools or professional services. Disquantified+1
Can beginners use online finance articles to learn about money?
Yes. Beginner-friendly articles can explain budgeting, saving, debt, investment terminology, and financial planning. The best approach is to use educational content to understand the fundamentals, then verify important details with reliable sources before making financial decisions.
How can I tell whether a financial website is trustworthy?
Check the author’s identity and qualifications, the quality of supporting evidence, publication dates, disclosures, and the site’s approach to risk. Verify important claims independently, especially when an article recommends a financial product or promises unusually attractive returns.
Is online financial advice suitable for investment decisions?
Online financial education can help readers understand investment concepts, but general articles may not account for individual circumstances. Investment decisions should reflect personal goals, time horizons, risk tolerance, fees, and tax considerations. A qualified professional may be appropriate for Finance www disquantified .org complex situations.
What financial topics should beginners learn first?
Start with budgeting, cash flow, emergency savings, credit, interest, debt repayment, and basic investing principles. These subjects provide a foundation for evaluating more advanced topics such as retirement planning, portfolio diversification, and tax-efficient investing.
How does financial data analysis help with budgeting?
Financial data analysis helps users identify spending patterns, compare actual expenses with planned budgets, and evaluate progress toward savings goals. Reviewing transactions over several months can reveal recurring costs or changes in spending that may otherwise go unnoticed.
Can technology replace a financial adviser?
Budgeting applications and digital tools can simplify calculations and organize information, but they do not necessarily provide personalized professional judgment. A qualified financial adviser can consider broader circumstances, including competing goals, tax implications, and risk exposure, when offering appropriate services.
Why should financial information be checked against official sources?
Official sources provide authoritative information on subjects such as tax rules, regulatory requirements, economic statistics, and investment disclosures. Checking primary documentation reduces the risk of acting on outdated figures, unsupported claims, or misleading interpretations.
What is the most effective way to improve financial literacy?
Build knowledge gradually, practice with your own budget, compare financial products carefully, and review decisions regularly. Focus on understanding costs, risks, and trade-offs instead of searching for a universal strategy that promises the same outcome for everyone.
Conclusion
Exploring finance through online resources can help readers develop a clearer understanding of budgeting, saving, borrowing, investing, and financial risk. Searches such as finance www disquantified .org can provide a starting point for finding relevant material, but the usefulness of that material depends on its accuracy, transparency, and practical value.
The strongest financial decisions combine reliable information with realistic planning. Track your cash flow, establish appropriate savings, understand the costs of debt, and evaluate investment opportunities in light of your own goals and circumstances.
Above all, remember that financial knowledge is a tool for making informed choices, not a guarantee of financial success. By verifying claims, recognizing uncertainty, and reviewing decisions over time, readers can build more resilient money-management habits and approach future financial challenges with greater confidence.

Comments are closed.
[…] Finance www disquantified .org How Financial Data Can Support Smarter Money Decisions […]